When looking to invest savings in real estate without managing a tenant or signing at the notary, one quickly encounters two options: REITs and listed property companies. However, listed property companies offer a very different profile, with almost immediate liquidity and minimal entry fees. Understanding what distinguishes them allows for clearer decision-making in a rapidly changing real estate market.
Energy constraints and the risk of stranded assets: what European standards change
A property owner of poorly insulated offices in Lyon or Frankfurt faces a concrete problem: European energy regulations are gradually raising performance requirements. Buildings that do not meet the thresholds lose rental value, or even become unlettable. This is known as the risk of stranded assets.
For an individual investor who owns an apartment, financing a major renovation directly impacts profitability. Listed property companies pool this cost across their entire portfolio, sometimes comprising several hundred buildings spread across different geographical areas. The ability to plan large-scale work, negotiate prices with construction companies, and absorb vacancy periods during renovations constitutes a structural advantage.
Sogaris, for example, has turned its ESG performance into a financing lever: its verified non-financial indicators allow it to adjust the cost of its loans. Detailed analyses of such mechanisms can be found in real estate articles on Influence News, which decode the role of property companies in current investment. ESG performance is becoming a financing factor, not just a marketing label.
Listed property companies and portfolio rotation: from office to residential
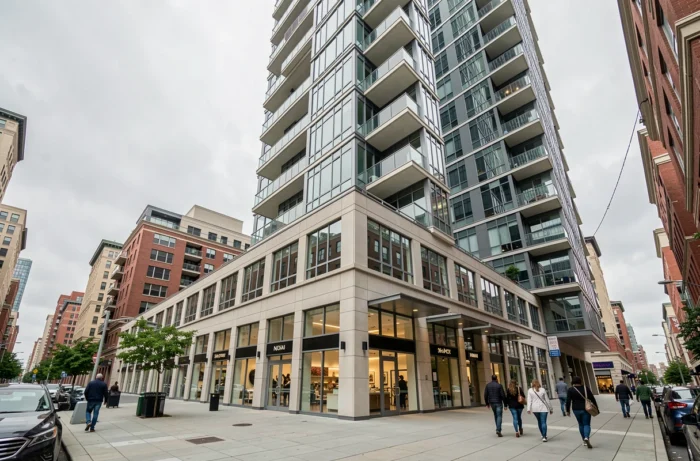
The market no longer treats all real estate assets the same way. In Europe, residential (housing, student residences, seniors) has become the most sought-after asset class, ahead of offices and retail. The housing shortage, demographic aging, and new lifestyles fuel this demand.
Listed property companies are adjusting their portfolios accordingly. Some are selling office towers to acquire residential buildings in cities with high rental pressure. This rotation would be impossible for an individual investor: selling an office building takes months, involves intermediaries, and incurs substantial fees.
Data centers, a new diversification axis
Beyond residential, data centers attract property companies seeking yield. Demand is exploding with the digitization of businesses and the development of artificial intelligence. In Spain, a proposed decree sets strict requirements for heat reuse and water consumption for centers exceeding a certain power threshold.
Exposure to data centers remains a sector bet with increasing energy constraints. Property companies investing in this segment must integrate environmental compliance costs that the market sometimes underestimates. Returns vary on this point depending on the location and size of the facilities.
Liquidity and taxation: comparing listed property companies and REITs on the ground
On paper, the liquidity of listed property companies is their main advantage over REITs. Shares can be bought and sold in seconds through a securities account or a PEA-PME, without a waiting period or redemption queue. In return, the price fluctuates like any stock on the market: a property company can lose several points in a session on an announcement of interest rate hikes.
This volatility destabilizes investors used to the apparent stability of REITs. With a REIT, the share price evolves slowly, giving a sense of security. The volatility of listed property companies reflects the real market price in real time, whereas REITs artificially smooth their valuations.
Concrete criteria for choosing between the two
- The investment horizon: listed property companies are better suited for an investor who can withstand temporary declines over a multi-year horizon without panicking at the first correction.
- The tax treatment of the investment: in a PEA-PME, some European property companies benefit from reduced taxation on capital gains after five years, an advantage inaccessible with a traditional REIT.
- The entry ticket: a few dozen euros are enough to buy a share of a listed property company, compared to several hundred or even thousands for a share of a REIT, not to mention subscription fees.
- The need for regular income: SIICs (Sociétés d’Investissement Immobilier Cotées) are required to distribute a significant portion of their profits as dividends, generating a recurring income stream.
Interest rates and discount: when the market undervalues real assets
The rise in interest rates since 2022 has caused the prices of many listed property companies to fall well below the book value of their assets. In concrete terms, one could buy real estate on the stock market for a price lower than what it would cost to directly acquire the same buildings.
This discount represents an entry window for patient investors. When rates stabilize or decline, the prices of property companies gradually readjust towards the real value of the assets held. The mechanism works both ways: in periods of low rates, listed property companies sometimes trade at a premium to their net asset value.
Analyzing a property company requires looking beyond the stock price. The debt ratio (loan-to-value), the quality of tenants, the remaining lease duration, and the location of assets determine the actual strength of the company. A controlled debt ratio protects better than a high dividend in times of market stress.
Listed property companies do not replace direct real estate investment or REITs. They occupy a specific place in a diversified portfolio, between the stock market and real estate. Their ability to pivot quickly to new asset classes (residential, logistics, data centers) and to integrate regulatory constraints makes them a more agile tool for real estate exposure than most alternatives available on the market.